

6G Futures special edition — April 12th, 2026
Last Friday’s newsletter covered the HAPS Alliance white paper, “6G from the Stratosphere,” which maps High Altitude Platform Stations (HAPS) into the emerging three-layer 6G network architecture. Given all the recent attention on satellite-based non-terrestrial networks (NTN), it is worth spending a little more time looking at this proposal. HAPS is one of those technologies that has been perpetually five years away from commercial viability, yet the convergence of 6G standardisation, WRC-23 spectrum decisions and real pre-commercial activity from operators suggests the picture may finally be changing.
The HAPS Alliance counts four telecom operators among its members: Deutsche Telekom, SoftBank, KDDI and NTT DOCOMO, alongside aerospace firms including Airbus (via its spinout AALTO HAPS), AeroVironment, Sceye, Thales and BAE Systems, as well as research institutions and technology providers. Those operators are not fringe players. Whether their endorsement translates into standards traction and deployment budgets is the big question.
The HAPS Alliance white paper: what it says
The new white paper positions HAPS as the stratospheric middle layer in a three-tier 6G architecture comprising surface (terrestrial), stratosphere (HAPS at approximately 20 km altitude) and space (satellite). It is a 23-page document that moves beyond promotional generalities into quantitative KPI comparisons and use-case-specific analysis. That alone makes it more useful than many of the NTN press releases that have circulated in the past year.
The core technical argument rests on a link budget advantage. At 20 km altitude, a HAPS platform sits roughly 25 times closer to the ground than a LEO satellite at 500 km. The white paper calculates that this proximity yields approximately 28 dB less free-space path loss at the same frequency, directly translating into higher signal-to-noise ratios and the ability to serve standard smartphones without requiring dedicated terminals. This is the Direct-to-Unmodified-Smartphone (D2US) proposition, and it is the single most important differentiator HAPS claims over satellite.
The latency numbers are similarly distinct. Round-trip propagation delay from a 20 km nadir is approximately 0.13 ms, compared with roughly 3.3 ms for LEO at 500 km, 60–200 ms for MEO, and over 480 ms for GEO. The white paper sets a target of 1–10 ms end-to-end latency for HAPS with regenerative (on-board processing) payloads, placing them in a performance envelope between terrestrial 6G and LEO satellite.
Coverage per platform is estimated at 50–100 km radius, with massive-MIMO beamforming enabling dynamic capacity shaping. Deployment speed is measured in hours or days, compared with the months or years required for satellite constellation launches.
The paper maps these capabilities against five priority use cases:
Integrated Sensing and Communication (ISAC): HAPS is rated as “high applicability” for drone control, disaster early warning and public safety, and “moderate” for panoramic scanning and precision sensing. Industrial automation is rated “limited” due to indoor penetration constraints. A word of caution though: as we heard during last week’s 3GPP/ATIS webinar, the commercial case for ISAC is still unclear and there is currently little urgency in including ISAC in Release-21. The HAPS Alliance may want to rethink this one.
Direct-to-Unmodified-Smartphone (D2US): Positioned as the primary connectivity use case for coverage gaps in mountainous terrain, remote islands, ocean, suburban areas and airspace. Downlink user rates of approximately 500 Mbps and uplink of approximately 50 Mbps are cited as feasible with mmWave spectrum and dynamic beam management.
Disaster recovery: HAPS platforms can be pre-positioned or rapidly deployed to provide 50–100 km radius coverage, serving as both direct-to-device access and temporary backhaul for surviving terrestrial cells. The paper emphasises that HAPS, operating in the stratosphere, are immune to ground-level disruptions.
Vehicular connectivity (C-V2X): The white paper evaluates thirteen C-V2X use cases against HAPS latency capabilities. It concludes that five can be served by both HAPS and LEO, four can be served exclusively by HAPS (including cooperative lane change and normal-density platooning), and only one (emergency trajectory alignment at ≤3 ms) is likely beyond HAPS capabilities.
Shared networks and neutral hosts: HAPS operating as neutral-host platforms could serve multiple operators through MOCN or MORAN configurations, with potential for multi-RAT support across LTE, NB-IoT and 5G NR. This is a business model argument as much as a technical one.
Note that the KPI targets (500 Mbps downlink, 1–10 ms latency) are theoretical targets under favourable conditions, not field-verified operational benchmarks. Also, the C-V2X use case analysis relies on qualitative assessment rather than measured data. Whilst the HAPS Alliance is a credible industry body, the white paper is a positioning document rather than an independent technical evaluation.
Background: the long road to the stratosphere
The idea of using stratospheric platforms for communications is not new. The concept dates back to at least the 1990s, when the ITU first began studying HAPS, and early demonstrator programmes emerged in the mid-1990s. The journey since then has been marked by ambitious visions, significant technical achievements and a string of commercial failures.
The pioneers:
The highest-profile casualty was Google’s Project Loon. Launched as a Google X “moonshot” in 2011, Loon used stratospheric balloons to deliver LTE connectivity. It achieved genuine technical milestones: a pilot service in Kenya, over one million hours of cumulative stratospheric flight, and a single-balloon endurance record of 312 days in 2020. But balloons drift. Loon needed roughly eight times the number of platforms to maintain persistent coverage over a given area, and the economics never closed. The project was spun out as an Alphabet subsidiary in 2018 and shut down in January 2021. SoftBank, which had invested in Loon, subsequently acquired some of its patents.
Facebook’s (now Meta’s) Aquila programme followed a different approach: a carbon-fibre, solar-powered fixed-wing UAV with a huge 40-metre wingspan. Its first flight in 2016 ended in a crash when a section of the wing broke off during landing. A second test flight in 2017 went better, but Facebook abandoned the project in 2018.
The Airbus Zephyr has had the longest development arc. Originally created by QinetiQ in the early 2000s, with a first flight over Australia in 2005, the programme was acquired by Airbus in 2013. The Zephyr S set an endurance record of 25 days in 2018. A subsequent US Army-sponsored flight in 2022 reached 64 days before the aircraft was lost in the Arizona desert, just hours short of beating the all-time continuous flight record. Two earlier Zephyr crashes in Australia in 2019 were attributed to turbulence. In late 2023, Airbus spun the programme out into AALTO HAPS. AALTO has since established a dedicated launch facility in Kenya and claimed a 67-day Zephyr endurance record in early 2025.
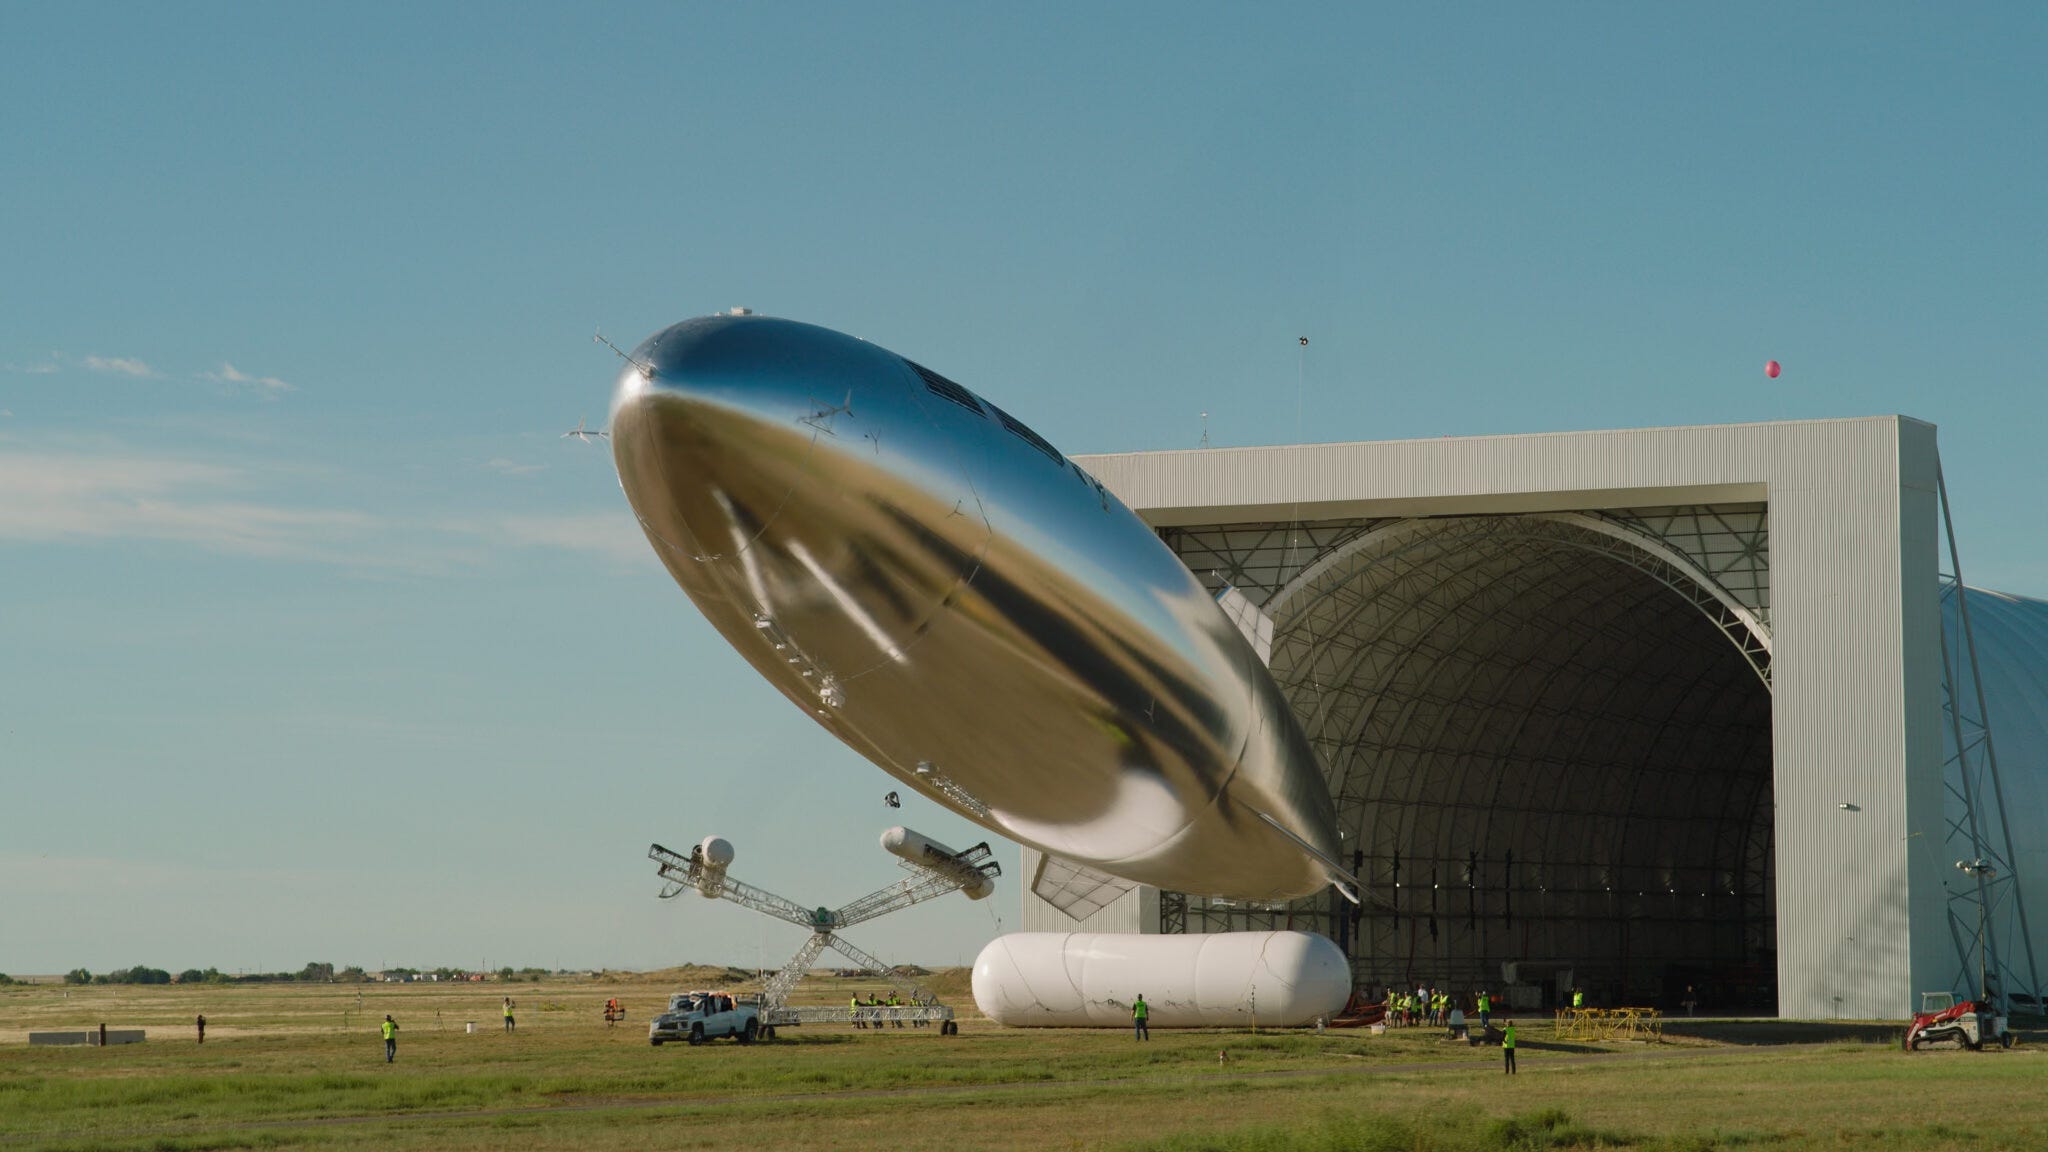
SoftBank has been the most persistent telecoms investor in HAPS. It established HAPSMobile in 2017 as a joint venture with AeroVironment, building the Sunglider, a 78-metre wingspan solar-powered aircraft. A stratospheric test flight in September 2020 was followed by the world’s first 5G communication from the stratosphere in Rwanda in September 2023. In October 2023, SoftBank absorbed HAPSMobile into its main corporate structure. In June 2025, SoftBank invested $15 million in Sceye, a New Mexico-based company developing lighter-than-air HAPS (a helium airship – see the accompanying photo), securing exclusive rights to provide HAPS services in Japan using Sceye’s platform. Pre-commercial HAPS services in Japan are scheduled for later in 2026, initially focused on disaster recovery and connectivity to remote areas.
The regulatory unlock:
A critical milestone came at WRC-23 in Dubai, where the ITU identified the 700–900 MHz, 1.7 GHz and 2.6 GHz mobile spectrum bands for HAPS use as IMT base stations (HIBS), accompanied by operational regulations. This built on WRC-19 decisions that had already identified mmWave bands (31 GHz, 38 GHz, 47 GHz) for HAPS. The WRC-23 decisions are significant because they allow HAPS to operate on the same frequencies and serve the same devices as existing mobile networks, removing a major barrier to the D2US proposition.
Both Sceye and AALTO HAPS are the only companies to have demonstrated full diurnal (day-and-night) stratospheric flight, a key milestone for proving persistent coverage capability. NTT DOCOMO is partnering with AALTO for commercial Zephyr demonstrations over Japan, also targeting 2026. The HAPS industry appears to be moving from technology demonstration to pre-commercial validation, though full commercial operations remain ahead.
HAPS in the 3GPP 6G standards process
HAPS does not appear in the 3GPP 6G standardisation process as a standalone study or work item. It sits within the broader NTN framework, which is primarily driven by satellite interests. This positioning is both a strength and a vulnerability.
At the 3GPP 6G Workshop in March 2025, NTN was one of the most heavily represented topics, with submissions from Thales, Airbus, ESA, SoftBank, CSCN, Viasat/Inmarsat, GSOA, Sky Perfect JSAT and a joint submission from 30 companies led by Thales. The overwhelming consensus was that NTN must be integrated into 6G from day one, avoiding the late incorporation that hampered 5G NTN (which did not appear until Release 17). There is near-universal agreement on the need for GNSS-independent operation, seamless TN/NTN handovers and multi-layer 3D network architectures.
However, the workshop submissions reveal a clear hierarchy of priorities. Satellite operators dominate the NTN conversation. LEO and GEO constellations are the primary focus, with HAPS mentioned explicitly by only a handful of contributors. SoftBank identified HAPS as enabling “ubiquitous coverage and disaster-resilient networks.” Thales noted that NTN, including HAPS, is critical for disaster relief. Airbus called for “unification” of terrestrial and NTN-RAT as a 6G objective and specifically advocated for multi-layer 3D architectures. But these are supporting mentions rather than dedicated HAPS advocacy within the standards process.
The NTN Top Ten priorities extracted from workshop submissions focus on satellite-centric requirements: multi-orbit cooperation, spectrum sharing and direct-to-device connectivity. HAPS-specific requirements, such as regenerative payload standardisation, HAPS-terrestrial interference management and stratospheric mobility management, are not explicitly called out as distinct items. The risk is that HAPS requirements get subsumed into a satellite-dominated NTN specification that does not fully accommodate the distinct characteristics of stratospheric platforms.
At RAN #109 and #111, NTN deployment scenarios have been captured in TR 38.914, though the discussion has been primarily framed around satellite access. The Release 21 timeline, with Stage 1 freeze in March 2027 and ASN.1 freeze in March 2029, leaves limited space for new work items that do not already have strong champion support.
Does 6G HAPS have a chance?
Let’s be honest: HAPS faces a narrow path to meaningful inclusion in 3GPP Release 21. However, there is a more promising trajectory in subsequent releases and in commercial deployment outside the standards timeline.
The case for inclusion:
The 6G architecture explicitly embraces multi-layer networks. The IMT-2030 vision framework highlights ubiquitous connectivity as a pillar use case, and the 3GPP workshop outputs reference 3D unified networks. HAPS occupies a distinct performance niche that satellite cannot fully replicate: lower latency, higher per-user throughput and faster deployment. The WRC-23 HIBS spectrum decisions provide regulatory legitimacy. Four operators in the HAPS Alliance (Deutsche Telekom, SoftBank, KDDI, NTT DOCOMO) are also active 3GPP contributors, and SoftBank’s pre-commercial 2026 deployment in Japan could generate real operational data to inform standardisation.
The case for scepticism:
HAPS has no dedicated champion rapporteur for a 6G study item. The NTN conversation in 3GPP is satellite-dominated, with powerful industry coalitions (the 30-company Thales-led submission, GSOA, major satellite operators) focused on orbital systems. Release 21 is already capacity-constrained, with the timeline spanning just two years of normative work. Adding HAPS-specific specifications would compete for attention against higher-priority items including AI-native RAN, new radio waveforms, FR3 spectrum and core architecture migration. The commercial HAPS ecosystem remains tiny compared with the satellite industry, and no operator has yet deployed HAPS at scale.
The failure history matters. Project Loon, Facebook Aquila and multiple Zephyr crashes demonstrate that stratospheric operations remain technically demanding. Even the most advanced platforms (Sceye, AALTO) have only demonstrated endurance of weeks to months, not the year-round persistent coverage that a commercial service requires. Fleet management, maintenance logistics and regulatory frameworks for routine stratospheric operations are all immature.
Most likely outcome:
Release 21 will almost certainly include HAPS within the broader NTN framework, but without HAPS-specific normative work. The multi-layer architecture text will accommodate stratospheric platforms in principle, and the existing NTN specifications (particularly around D2US and disaster recovery) will be applicable to HAPS. Dedicated HAPS standardisation is more likely to appear in Release 22 or beyond, once pre-commercial deployments in Japan have generated operational data and if operator demand materialises.
The commercial path may run ahead of standards. SoftBank and NTT DOCOMO are pursuing HAPS deployment using existing 4G/5G spectrum and standards frameworks, which is entirely feasible under WRC-23 HIBS provisions. If these deployments succeed, they will create the evidence base that could drive dedicated HAPS standardisation for 6G. If they do not, HAPS will remain an interesting architectural concept without the commercial gravity needed to command standards attention.
The stratospheric middle layer is real. Whether it becomes routine infrastructure or remains a niche curiosity depends less on the technology, which is now demonstrably viable, and more on whether operators see a business case that justifies the investment.
For disaster recovery and coverage extension in geographically challenging markets like Japan, that case is emerging. For the broader global market, it remains unproven.
Wonderfully clear Guy. But I'm sure many of us are wondering how the new emphasis on technical and communications sovereignty might feed into long-term HAPS prospects? Operating within the stratosphere must afford jurisdictional control regarding spectrum assignments, national legal requirements to middle and below powers with small geographies. LEOs are the opposite. So
who the hell wants to share crucial comms infrastructure with an avowed anti-European like Elon Musk? (asking for 27 friends - hopefully soon to be 28 again)